Blog
Via an Interview with Ron Lang, By Phil Calhoun
As CalCPA Health celebrates its 66th anniversary, its story stands as a testament to the power of community-driven solutions in the often-turbulent world of health insurance. In this first installment of a three-part series, California Broker Media CEO Phil Calhoun sat down with Ron Lang, CEO of CalCPA Health, to explore the unique structure, mission, and value CalCPA Health brings to California’s financial professionals. This article also incorporates insights from industry sources and regulatory data to provide a broader context.
A Unique Legacy Born From Necessity
CalCPA Health was founded in 1959 by the California Society of Certified Public Accountants (CalCPA) to address a persistent problem: small employers, especially in financial services, had difficulty obtaining and maintaining health insurance. According to the U.S. Small Business Administration, small businesses have historically faced higher premiums and fewer choices than larger employers, due in part to limited bargaining power and risk pools (SBA, 2023). Ron Lang, who has led CalCPA Health for 13 years, explained, “Not very many businesses make it 66 years, especially in the health insurance business where we’ve had the government trying to put us out of business for the last years.
So, it’s quite an accomplishment.” The organization’s model was to pool together small firms—often with fewer than 100 employees, and sometimes just three or four partners and staff—to create the critical mass needed for large employer-style benefits and rate stability. Lang emphasized, “The whole idea behind CalCPA Health was to bring together a large volume of these smaller firms, to create critical mass to be able to provide them with large employer-style benefits and spread that risk out to provide rate stability and a really large group product to these small employers. And it’s worked for decades, obviously, we’re still around.”
Not-for-Profit and Standalone: A Different Kind of Carrier
Unlike many association health plans, CalCPA Health is a licensed, admitted, not-for-profit insurance carrier domiciled in California. This distinction is significant. While association health plans have drawn scrutiny from regulators for sometimes lacking transparency or sufficient consumer protections (Kaiser Family Foundation, 2022), CalCPA Health operates under strict state oversight. Lang clarified, “We are an insurance carrier. We’re domiciled in the state of California, we’re licensed, we’re an admitted carrier. Although we are married to the CalCPA, the society, we are a standalone entity. We’re a not-for-profit. So, our loss ratios and things are much better than what the national commercial insurance companies put out there.” This not-for-profit status allows CalCPA Health to focus on long-term rate stability and value-added services, rather than maximizing shareholder returns. “We’ve been able to offer long-term rate stability, products that are tailored to the industry, and a lot of additional value adds—what we call non-premium value adds—to the mix. We give a good value proposition to these employers,” Lang said.
Leveraging Anthem’s Network for Nationwide Access
A key feature of CalCPA Health’s offering is its partnership with Anthem, one of the largest provider networks in the country. According to the California Department of Managed Health Care, broad network access is a top priority for employers and employees alike (DMHC, 2024).
Lang explained, “We rent Anthem’s large group provider network, and there’s a couple reasons for that. One is that we wanted to give the best access to our members to providers in the state of California and nationally, because a lot of firms are domiciled here but have employees scattered around the country. That provides us with that national network.” He added that this arrangement also streamlines the member experience: “When they walk in with our logo and the Anthem logo on that card, the doctor immediately knows how to get access to the benefits and if there’s authorizations or deductibles. That’s all immediately accessible to the docs because we’ve partnered with Anthem.” This partnership has been in place since at least the late 1960s, giving CalCPA Health members reliable access to care for decades.
Plan Design and Transparent Underwriting
CalCPA Health designs and rates its plans internally, using in-house actuaries and external consultants. This is a departure from many association plans, which often rely on external carriers for plan design and pricing. “We design and rate the plans from scratch ourselves. We have in-house actuaries and then we have an actuarial consulting firm to sign off on things. So, we create the plans, design the benefits, and then we do the ratings on all of our plans,” Lang said. Membership eligibility is broad, encompassing not only CPAs but also a range of financial professionals, including wealth managers and insurance agencies. For partnerships and S-corps, at least half the ownership must be CalCPA members; for publicly traded companies, the executive teams qualify.
“Our data has shown that people tend to go to the doctor around their home rather than necessarily their place of work”.
On the underwriting side, CalCPA Health has always been 100 percent community rated, even before the Affordable Care Act (ACA) required it. Community rating, as defined by the ACA, means that premiums are not based on an individual group’s health status but rather on broader risk pools, promoting fairness and stability (Healthcare.gov, 2024). Lang noted, “Whether it’s a large group or small group, we community rate across the entire book of business and we’ve always had to file all of our rates with the Department of Insurance. It’s all very transparent as far as what our rates are.”
CalCPA Health also rates employees based on their home zip code, which often results in more competitive rates. “Our data has shown that people tend to go to the doctor around their home rather than necessarily their place of work. By rating at the employee zip code, we’re segmenting better and it tends to make us a little bit more competitive,” Lang shared.
Rate Stability: A Key Value
CalCPA Health’s record of rate stability is especially important for small businesses. According to a 2023 survey by the National Federation of Independent Business, unpredictable health insurance costs remain a top concern for small employers. Lang explained, “The last time we were in double digits was coming out of the Affordable Care Act when we had total chaos. Over the last eight or nine years, if you add up each of the increases, we come out below four percent over that period of time.”
He continued, “If you’re running a business, particularly a small business, and you get hit with a 15 or 20 percent rate increase, I’m just not sure how you run your business while you’re doing that. For most of these financial services and CPA firms, their health plan costs are usually higher than IT, higher than rent. The only cost that’s more than that is salaries. So, it’s a big number.”
Looking Ahead
As CalCPA Health continues its mission, its not-for-profit model, transparent practices, and commitment to member value remain its guiding principles. In the next installment of this three-part series, Ron Lang will discuss the evolving challenges facing California’s financial professionals and how CalCPA Health is adapting to meet those needs in a changing healthcare environment.
Part 2 Coming Next Month
CalCPA Health: 66 Years of Service & Stability for California’s Financial Professionals
Via Interview with Ron Lang By Phil Calhoun
When it comes to healthy eating, most of us have heard of the Mediterranean Diet, but have you heard of the Atlantic Diet? Originating in northern coastal regions of Portugal and Spain, the Atlantic Diet offers a delicious alternative with its unique spin on healthy living.
What Is the Atlantic Diet?
The Atlantic Diet is based on the traditional eating habits of communities along the Atlantic coast of Spain and northern Portugal. Much like the Mediterranean Diet, it emphasizes fresh, seasonal foods and lifestyle habits that prioritize community and physical activity. But the main differences lie in the types of foods, cooking methods, and the availability of ingredients.
Atlantic vs. Mediterranean: What’s the Difference?
| Category | Mediterranean Diet | Atlantic Diet |
| Main Protein Sources | Fish, poultry, legumes, moderate dairy | More emphasis on fresh fish, shellfish, lean pork, and dairy |
| Cooking Fats | Extra virgin olive oil | Olive oil is used, but also animal fats in small quantities, especially in rural areas |
| Vegetables | Tomatoes, eggplant, leafy greens, zucchini | Cabbage, potatoes, turnip greens, onions, carrots |
| Grains | Whole wheat bread, pasta, couscous, barley | More potatoes, corn-based dishes, and rye bread |
| Dairy | Typically, lower-fat dairy, yogurt, and feta | Higher dairy consumption, especially milk and cheese |
| Wine | Red wine, usually with meals | Moderate wine, but also cider and beer |
| Climate | Warm, dry | Cooler, wetter—supports different crops and cooking traditions |
Benefits of the Atlantic Diet
Studies suggest that the Atlantic Diet may offer comparable cardiovascular benefits to the Mediterranean Diet. It’s rich in omega-3 fatty acids (from seafood), fiber (from vegetables and whole grains), and antioxidants. A 2024 study published in JAMA Network Open examined the impact of the traditional Atlantic Diet on metabolic health in the Galician population. The study took place over six months and found a 68% reduction in metabolic syndrome among participants who followed the Atlantic Diet compared to a control group.
Health highlights include:
- Reduced risk of heart disease and stroke
- Improved gut health due to high fiber intake
- Anti-inflammatory effects
- Support for sustainable, local agriculture and seasonal eating
The Atlantic Diet may not be as well-known as the Mediterranean Diet, but its focus on whole foods, seafood, and lifestyle makes it desirable to those seeking a balanced and tasty way of eating.
Trump’s “One Big Beautiful Bill” (OBBB), passed on July 4, 2025, initially promised significant changes to Health Savings Accounts (HSAs). However, the final version of the legislation contained modest updates to HSA policy. Current HSA holders get to keep what they have, but significant reforms such as extending eligibility to those on Medicare or relaxing contribution restrictions, were abandoned in negotiations. Instead, the bill primarily focuses on restructuring Medicaid and welfare programs, implementing work mandates, and providing tax credits tied to families and newborn savings accounts.
Health Saving Accounts were thought to have a larger presence in the bill that would have placed HSAs as a centerpiece of healthcare funding and provided areas for growth by softening regulations of who can contribute, such as those on Medicare Part A. Without eligibility expansion, HSAs remain mostly unchanged, and tax-advantaged growth remains limited to current users.
Here’s a breakdown of what changes OBBB brings to HSA plans:
- If you are enrolled in a Bronze or Catastrophic ACA plan, you are now eligible to contribute to HSAs starting January 1, 2026.
- HSA funds can be used for Direct Primary Care (DPC) arrangements. DPCs typically follow the model of a monthly fee, which covers office visits prior to meeting the HDHP deductible. With OBBB, these monthly fees now fall under qualified HSA expenses if they do not exceed $150/month for an individual or $300/month for families.
- First-dollar coverage for telehealth services no longer disqualifies HSA status, which allows plans to provide low or no-cost telehealth services before satisfying your deductible if you are enrolled in a qualified HDHP without using your HSA contributions.
HSAs remain a useful tool for eligible taxpayers and serve as a tax-savings vehicle.
Triple Tax Advantage
- Pre-tax Contributions – Money goes in tax-free, reducing your taxable income
- Tax-free Growth – Funds grow tax-deferred through interest and/or investments (no capital gains)
- Tax-Free Withdrawals – As long as funds are used for qualified medical expenses, withdrawals are tax-free
Saving for the Future
- You can invest your HSA balance (once you hit a threshold set by your carrier, allowing it to grow like a retirement account)
- Can be used in retirement tax-free for medical expenses, or after age 65, for any reason (income taxes apply only if not used for qualifying healthcare expenses)
HSA funds roll over year-to-year, and don’t have a use-it-or-lose-it rule like Flexible Spending Accounts (FSAs). Additionally, you can use your HSA funds for a wide range of expenses, including copays, prescriptions, dental and vision care, mental health services, and certain over-the-counter items (such as pain relievers, allergy medications, and first-aid supplies). Lastly, you OWN your HSA – it stays with you if you change jobs or retire. You control how and when it is used, allowing you to learn how they work and ensure you make the most out of the account.
While the “One Big Beautiful Bill” fell short of delivering the HSA expansion many had hoped for, it did make some notable improvements. It’s clear that Health Savings Accounts remain one of the most innovative tools for managing healthcare costs, both now and in the future. In today’s uncertain and costly healthcare environment, understanding and maximizing your HSA is essential. For those enrolled in an HSA, remember, it isn’t just a spending account — it’s a strategy.
Posted by CalCPA Health | July 2025
July is UV Safety Awareness Month, and it’s the perfect time to remind ourselves how important it is to protect our skin from the sun’s harmful ultraviolet (UV) rays.
Individuals with fair skin can sunburn in as little as 10-15 minutes of midday sun exposure when UV rays are the highest. UV rays are typically high between 10 a.m. and 4 p.m. and the highest around 11 a.m. to 1 p.m. Don’t let a cloudy day fool you because UV rays can be just as intense as on a sunny day.
What Are UV Rays?
Ultraviolet radiation from the sun comes in three forms:
- UVA rays penetrate deep into the skin and are responsible for premature aging, such as wrinkles and age spots, and can contribute to skin cancer.
- UVB rays are more intense and damage the outer layers of the skin, causing sunburns, and they play a key role in the development of most skin cancers.
- UVC rays are the most dangerous, but they are absorbed by the Earth’s atmosphere and don’t typically pose a threat during everyday sun exposure.
Types of Skin Cancer
Skin cancer is the most common cancer in the U.S., but it’s also one of the most preventable. Here are the three main types:
- Basal Cell Carcinoma (BCC): The most common and least aggressive type, accounting for approximately 80 percent of all cases*. It often appears as a flesh-colored bump or pink patch of skin and may bleed or form a scab. BCC grows slowly and rarely spreads, but it can cause local tissue damage if untreated.
- Squamous Cell Carcinoma (SCC): Accounts for approximately 20 percent of all skin cancer cases* and tends to occur on areas of the body most exposed to the sun, such as the face, neck, and hands. SCC shows up as a scaly red patch, a wart-like growth, or a sore that won’t heal. It can grow deeper and, in some cases, spread to other parts of the body.
- Melanoma: The most serious form of skin cancer, which accounts for about four percent of skin cancer cases*. Melanoma can develop from an existing mole or appear as a new dark spot. Early detection is critical since melanoma can spread quickly and be life-threatening if not caught early.
How to Protect Yourself
- Wear sunscreen every day with broad-spectrum (UVA/UVB) protection, SPF 30 or higher.
- Cover up with clothing, hats, and sunglasses that block UV rays.
- Seek shade between 10 a.m. and 4 p.m., when the sun’s rays are strongest.
- Avoid tanning beds, which emit concentrated UVA and UVB radiation.
Check Your Skin
Examine your skin regularly for changes in moles, new growths, or sores that don’t heal. When in doubt, get it checked out. Annual skin exams with a dermatologist are a smart step in preventing skin issues, and early detection is key. Protecting your skin today is an investment in your health tomorrow. Enjoy the sunshine safely.
* https://skinandcancerinstitute.com/july-is-uv-safety-month/
What is the name of your health plan? Who’s your insurance carrier? If you had to look it up right now to check, you’re not alone; many people are not sure. If you don’t know the basics, you won’t be able to take full advantage of your benefits.
Health insurance is a tool—but only if you know how to use it. You don’t want to be like so many people out there who experience a health emergency and must deal with the stress of not understanding their health care coverage in a time of trauma.
Knowing your health plan matters
Surprise Bills
- You may get a procedure for which you need pre-authorization, and did not know until you received an unexpected bill. This happens more often than you can imagine.
- If you don’t know whether your provider is in-network or out-of-network, or how your plan covers care, you are more likely to pay out-of-pocket for services that should have been covered.
Miss Out on Preventive Services
- Many plans offer 100% coverage for preventive services (such as mammograms, colonoscopies, and annual physicals), virtual visits, and wellness programs. But you can’t use benefits you don’t know you have.
You Can’t Advocate for Yourself Without the Basics
- Here are just a few of the ways understanding your plan helps you:
- Ask the right questions and go through the proper channels for care; reach out for help by calling your insurance provider
- Spot billing errors
- Take advantage of telehealth, HSA options, or mental health coverage (to name a few)
What You Need to Know – Today
At the very least, every health insurance subscriber should know:
- Your carrier (the company providing your insurance, such as Anthem, Delta Dental, and VSP)
- Your plan type (Health Maintenance Organization – HMO, Preferred Provider Organization – PPO, Exclusive Provider Organization – EPO, or Health Savings Account – HSA)
- Whether your plan is individual, employer-sponsored, or part of an association
How to Find These Items Quickly
- Check your insurance ID card – it typically lists the plan name and carrier
- Log in to your carrier’s member portal (the website usually is on the ID card) – this is where you will find your plan documents, benefits, and provider network information
- Download your carrier’s app and create an account so that you have access to your ID card at all times, as well as to your health and benefit information and plan summary (Summary of Benefits and Coverage – SBC)
- Ask your HR or firm administrator if you’re part of an employer or association plan
Then, take a few minutes to review your SBC, as it outlines the services that are covered, excluded, and the pre-authorization requirements. It also helps you understand what your plan will cover and what you may need to pay out-of-pocket for. Knowing the basics gives you power as a healthcare consumer and enables you to become your own best advocate.
Please don’t wait for an emergency to try and understand your health plan; familiarizing yourself with it now is a smart way to save time, avoid stress, and ensure you get the most from your benefits.
*********
Created by CalCPA in 1959 as The Group Insurance Trust of the California Society of CPAs, CalCPA Health has remained steadfast in its mission to provide quality “boutique style” health care solutions—from medical, dental and vision to life and long-term disability—with unparalleled convenience and stability. It helps ensure that members can navigate the challenges of health care with confidence and peace of mind. CalCPA Health offers exclusive health and benefit plans to members, and there is a high level of trust knowing that these plans are operated by individuals who understand the unique needs of the profession – CalCPA members.
The IRS recently released the contribution limits for Health Savings Accounts (HSAs) for 2026. In the upcoming year, we will see an HSA contribution limit increase to $4,400 for individuals and an increase to $8,750 for a family. The IRS implemented inflation-adjusted parameters for health savings accounts in Revenue Procedure 2025-19.
For 2026, individuals with self-only coverage can contribute up to $4,400 to their HSAs, up from $4,300 in 2025. Family plans can contribute up to $8,750, up from $8,550 in 2025. The IRS also noted that the 2026 catch-up contribution for those aged 55 and older will remain $1,000 for 2026, unchanged from 2025.
According to Fidelity Investments’ 2024 Retiree Health Care Cost Estimate, a single 65-year-old retiring can expect to spend an average of $165,000, or $330,000 per couple, in health care and medical expenses throughout retirement. These figures are up nearly 5% over 2023 and more than doubled from the first estimate in 2002. Understanding how to save and invest with an HSA plan is key to helping you plan for future expected and unexpected medical expenses.
If you are in an HSA and have questions about how to get the most out of the plan, CalCPA Health can help answer your questions. CalCPA Health is at the forefront of HSA adoption, offering the most HSA plan options in California. CalCPA members have a strong understanding of the tax benefits HSAs provide. Education is key, and CalCPA Health is here to help whether or not you are in one of our plans. We are a resource for you, so please feel free to ask questions by emailing info@calcpahealth.com.
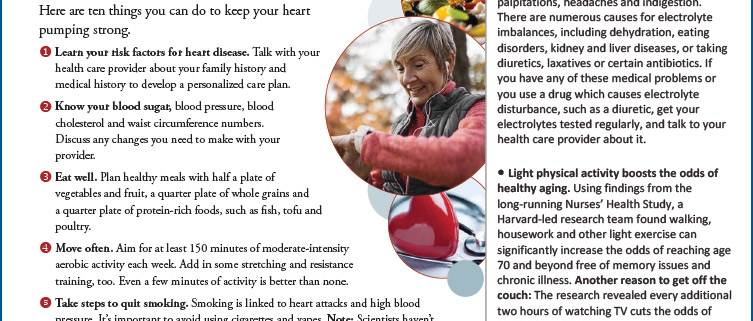
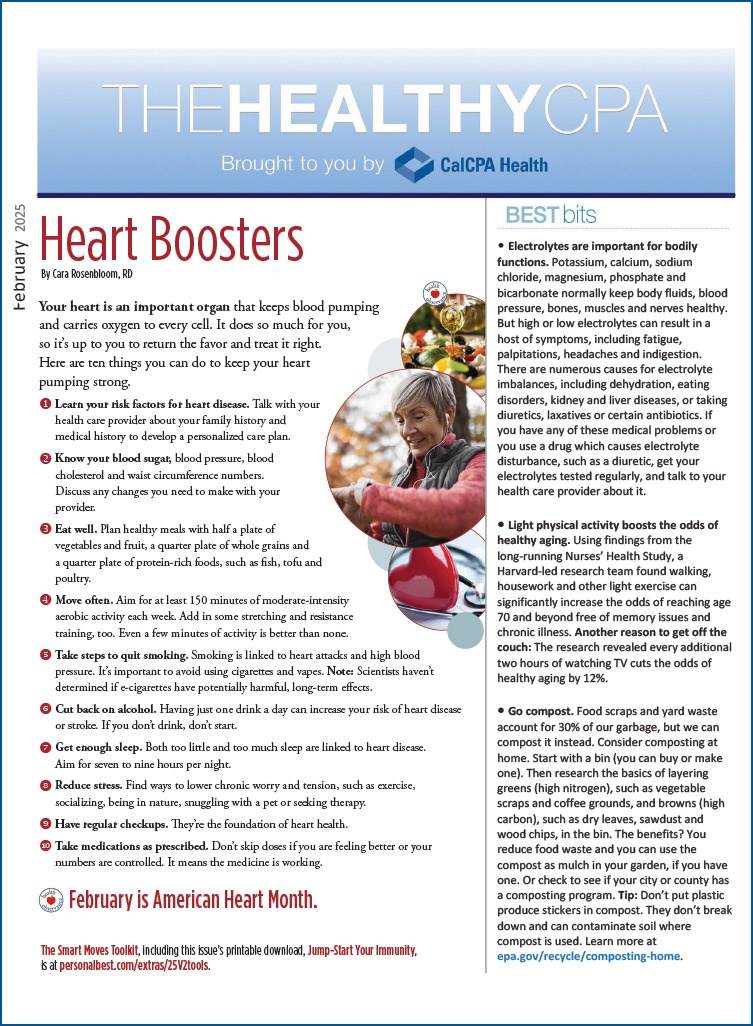 The eMagazine dedicated to improving members’ well-being
- Heart Boosters
- Helping Your Child Use Medication
- Home Medical Test Pros and Cons
- ASK THE DIETITIAN: Freezing Food
- Recipe – One-Pot Chicken Stew
In each issue you will find information and inspiration to help you with your health and wellness goals.
 The eMagazine dedicated to improving members’ well-being
- Health Fads You Don’t Need
- The Toll of Financial Stress
- Sleep and Mood
- The Science of Satiety
- Prebiotic Soft Drinks
- Recipe – Sheet Pan Honey-Mustard Chicken
- What is norovirus?
In each issue you will find information and inspiration to help you with your health and wellness goals.
 The eMagazine dedicated to improving members’ well-being
- Reverse Type 2 Diabetes?
- Video game addiction?
- Your Personal Exercise Plan
- Jazz Up Your Breakfast
- Ultra-Processed Foods and Long-Term Health
In each issue you will find information and inspiration to help you with your health and wellness goals.
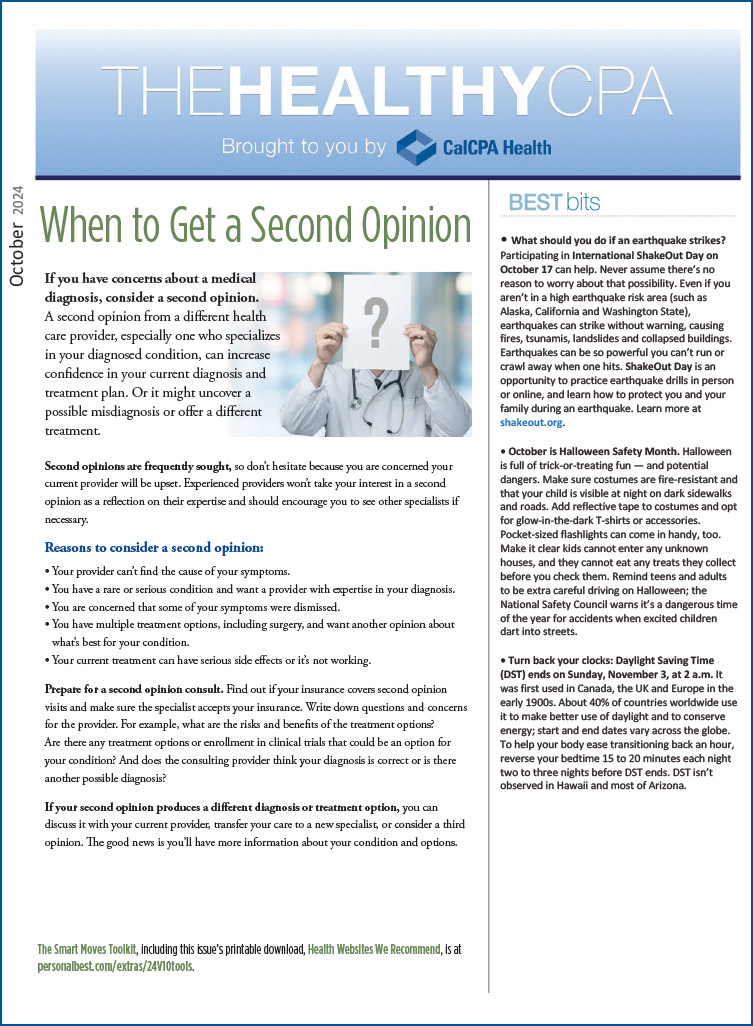 The eMagazine dedicated to improving members’ well-being
- When to Get a Second Opinion
- Protect Your Teeth
- Exercise Guidelines
- What is a diagnostic mammogram?
- Plant-Based Proteins
In each issue you will find information and inspiration to help you with your health and wellness goals.